


The euro and the pound rose in the first half of the day after October manufacturing PMIs, but they could not hold those gains for long. I do not expect that growth to continue, because the strong readings reflect costly inputs, prolonged delivery times, and precautionary stockpiling, not firmer demand within economies. The upcoming US session will refocus the market on the dollar and most likely will erase the remainder of the morning's impulse for both currencies.
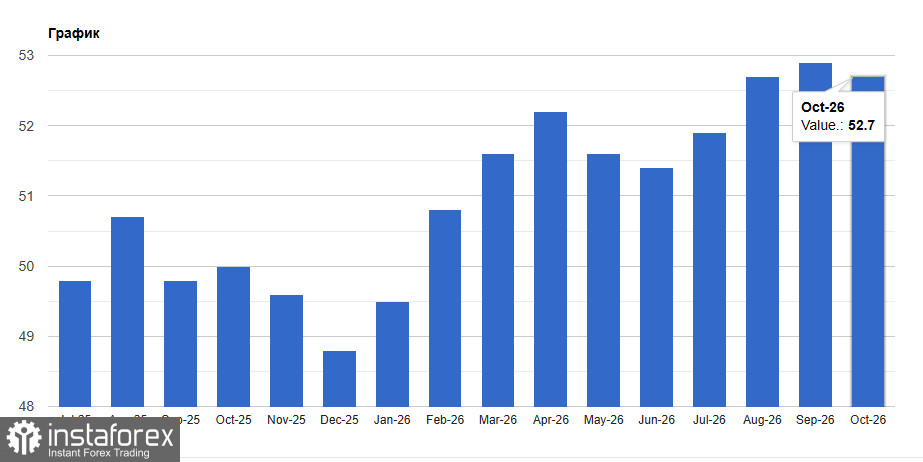
The October report for the eurozone looks decent on its own. Manufacturing PMI fell to 52.7 from 52.9 in September, but it beat economists' forecasts and remained in expansion for the ninth month in a row. This is a two-month low, yet September's 52.9 was the highest since May 2022, so I view the dip as mostly cosmetic. What matters more is the composition of the reading, because the components will shape the ECB's agenda in the coming weeks.
Output continued to grow, but the pace slowed to a four-month low, with the output subindex falling to 52.8 from 53.6 a month earlier. Inflow of new orders also weakened, while export orders rose at the fastest pace in more than four and a half years. Notably, that dynamic benefits factories oriented to external markets, primarily in Germany and the Netherlands, whereas firms dependent on domestic demand entered Q4 with noticeably less resilience.
I will draw attention to the survey's supply side. Delivery times lengthened in October at the fastest rate since June, and as a result the backlog of uncompleted orders rose at the quickest pace since May 2022. Recall that precautionary stockpiling during delivery delays is a classic defensive strategy, as firms buy today fearing that tomorrow will be more expensive and harder. The fear is not groundless, since expensive energy pushed inflation to the highest level since May. Manufacturers responded with sharp increases in selling prices, and the pace barely changed from September. It follows that rising input costs are currently pressuring industry margins and may reach consumers only later as a secondary effect.
Uneven growth adds to the ECB's headache. Of eight countries with available data, six showed expansion, and the pace of improvement in each case was historically strong. France and Italy returned to deterioration, and Paris also suffers from domestic political uncertainty. Where exports, defense orders, and stockpiling operate, factories are busy, but domestic demand is not providing the same support in France. Morning data on Germany also point to weak consumers: retail sales fell 2.0% in September versus an expected 0.4% increase.
UK manufacturing entered the fourth quarter noticeably stronger. Manufacturing PMI rose to 52.8 from 51.9 in September, hitting a five-month high and matching the preliminary estimate. Output rose for the seventh month in a row, at the fastest pace in 25 months, and the inflow of new orders accelerated to the strongest level since July, with demand improving from both domestic and overseas clients. Export orders rose for the tenth consecutive month, driven by sales to Brazil, mainland China, the EU, Middle Eastern countries, and the US. Growth covered consumer, intermediate, and investment goods, with investment goods output rising the most and intermediate goods the least. Firms' one-year business confidence rose to an eight-month high.
The second half of the report reads less encouragingly. Cost inflation accelerated, delivery times lengthened to one of the most pronounced degrees in four years, and inventories of purchased materials continued to decline. Employment remained unchanged after six straight months of hiring, because some firms, according to the survey, are postponing capacity expansion while trying to offset higher labor, transport, and raw material costs. In my view, the picture of rising output, stalled hiring, and accelerating costs argues for caution at the Bank of England and is unlikely to give the pound a durable footing.
Next, initiative will likely shift back to the dollar. The ISM manufacturing index for October is forecast at 54.7 versus 54.5 in September, and its price component is expected at 77.2 after 77.9 previously. If US purchasing prices surprise higher again, the market will conclude that inflationary pressure persists and will revise Fed rate expectations toward slower easing, which would support the dollar. I will add US construction spending for September, where the consensus is for 0.3% after 0.9%. A weak print would give the euro and the pound some relief, but I do not expect it to outweigh the ISM if that report comes in above forecasts.
If the ISM disappoints or if a speech by Bundesbank President Joachim Nagel sounds hawkish, the euro could hold near the morning highs for a while longer. Even then, I do not see European figures justifying sustained gains, because the market buys growth and then starts to count its cost. I expect EUR/USD and GBP/USD to resume declines in the coming sessions, with the morning impulse being an episode rather than the start of a new trend.
Technically for EUR/USD, buyers now need to think about taking 1.1230. Only then would a test of 1.1260 be possible. From there a move to 1.1290 is feasible, but doing so without support from major players will be difficult. On a decline, I expect serious buying interest only around 1.1200. If there is nobody there, it would be prudent to wait for a fresh low at 1.1170 or to open long positions from 1.1140.
Technically for GBP/USD, pound buyers need to take the nearest resistance at 1.3440. Only then would a move to 1.3467 be possible, above which further breakout will be quite difficult. The furthest target is the 1.3492 area. On a drop, bears will try to seize control of 1.3400. If they succeed, a range breakout would inflict serious damage on bulls' positions and push GBP/USD toward a low of 1.3380 with a prospect of extending to 1.3350.


